

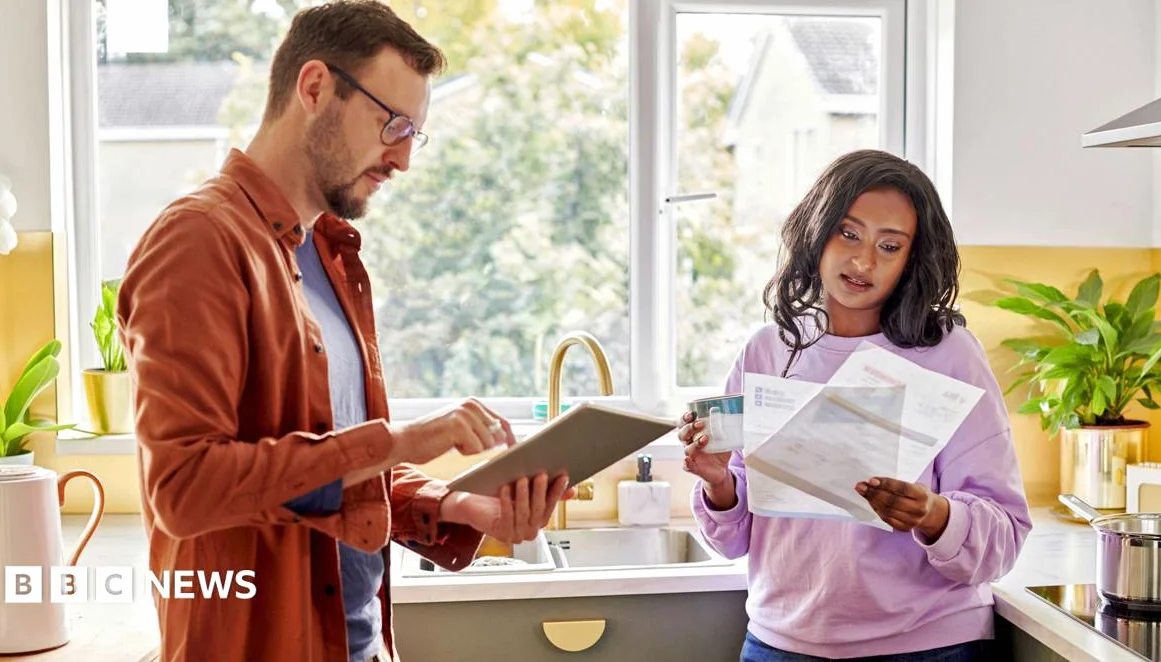
One million more UK homeowners are expected to face higher mortgage costs in the coming years, according to the Bank of England. A typical owner-occupier rolling off a fixed-rate deal in the next two years could see a £45 increase in their monthly bill, according to the Bank. That compares to a typical rise of £120 for those getting a new deal between the end of 2022 and end of 2024.
Fixed-Rate Deals and Rising Costs
However, 750,000 homeowners who are paying less than 3% interest on their current deals are expected to roll off these products this year and see an average increase of £170 per month in repayments, the Bank said. These increases are already impacting individuals like Saima Siddiqui, who is soon to refinance her one-bedroom flat in Surrey for the first time.
“It means I’m going to have to be more careful with other things,” the 33-year-old said; “It was alright as it was, but the extra £200 means I’m going to have to budget a lot more carefully. It was quite a surprise that the jump was so much, as I know I had a good deal, but it is quite worrying. If it does continue to increase in the same way, it is difficult to continue to live at the same standard if your salary doesn’t increase in the same way.”
Living on her own, Siddiqui had managed to get a 1.8% fixed rate for five years when she bought her first home.
Fixed-Rate Mortgages and Market Projections
More than eight in 10 mortgage customers have fixed-rate deals. The interest rate on this kind of mortgage does not change until the deal expires, usually after two or five years, and a new one is chosen to replace it. More than two million borrowers on a two-year fixed deal expiring by the end of 2028 were projected to remortgage close to their existing rate and see little change in repayments, the Bank said.
However, these borrowers are now unlikely to see repayments fall over coming years, as had been forecast prior to the Iran conflict — this suggests that the market is shifting, with fewer opportunities for reductions in monthly mortgage payments as rates stabilize or increase.
Broader Implications for Homeowners
The Bank of England’s projections indicate a challenging financial area for many UK homeowners; With interest rates unlikely to fall further in the near term, many borrowers may find themselves facing higher monthly outlays. This could have a knock-on effect on consumer spending and overall economic activity as households adjust their budgets to accommodate these increases.
For those with fixed-rate mortgages expiring soon, the transition to new deals could be particularly difficult given the current market conditions, and Siddiqui’s experience is a case in point, where even a small jump in mortgage payments has significant implications for her overall financial planning.
Comments
No comments yet
Be the first to share your thoughts